A Toronto average is rarely a useful personal budget. Rent and commute choices can change the result by thousands of dollars. Build your first three months from prices you can verify now.
Begin with money you can actually use
List the cash available on arrival, expected take-home income and the date each amount becomes available. Keep immigration proof-of-funds requirements separate from the household budget; under the applicable rules, some money may need to remain available and unencumbered.
Now make a low, expected and high plan for the first three months. In the low case, assume work starts later than hoped, the exchange rate moves against you and one appliance or dental visit cannot wait. The point is to see which choices need room to change.
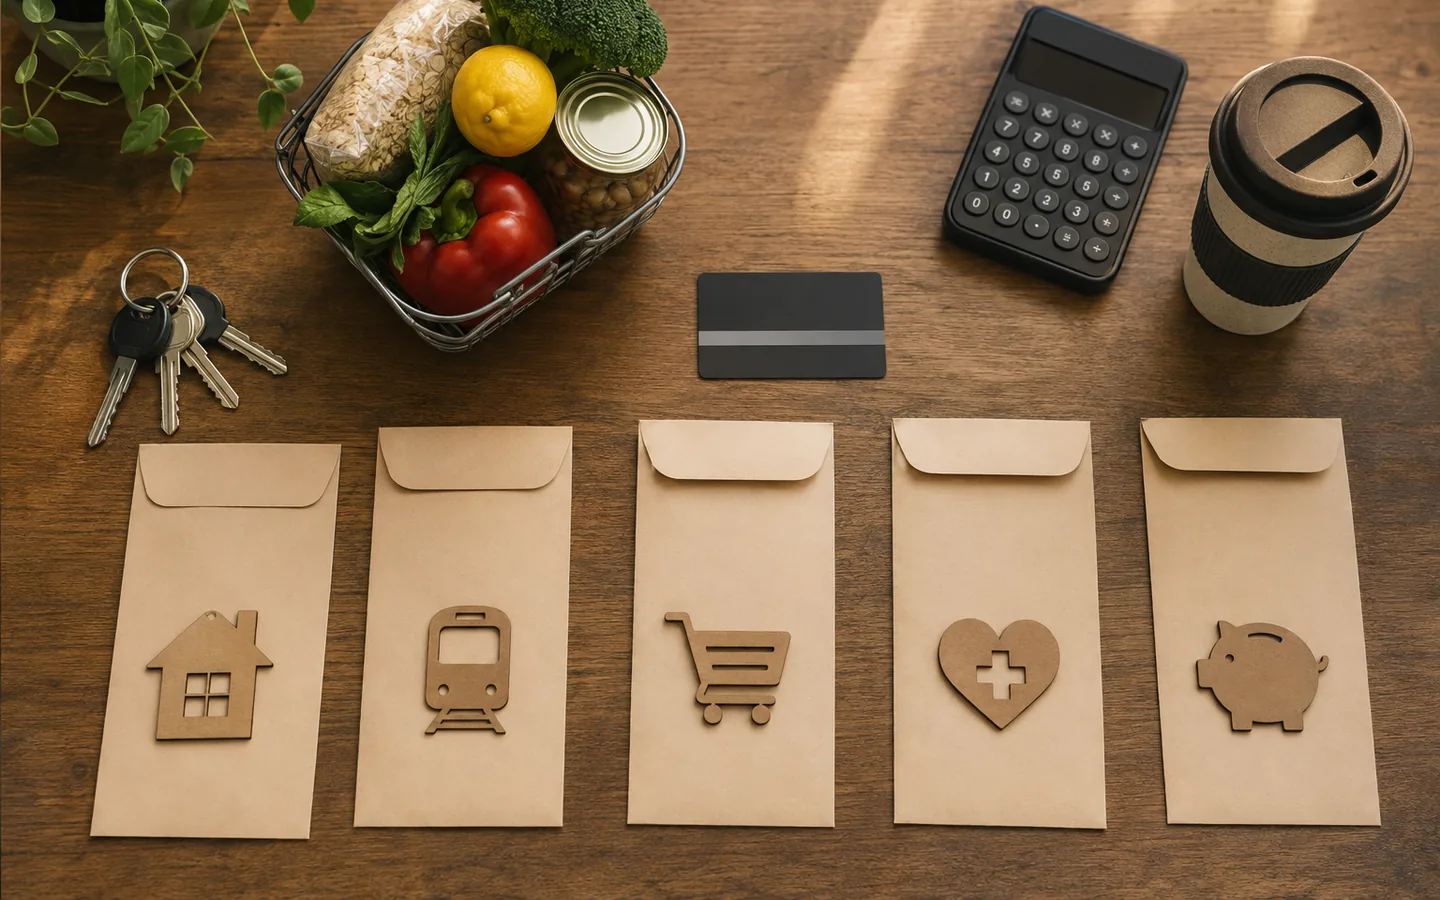
- 1Housing
- 2Transport
- 3Food
- 4Health
- 5Reserve
Rent is only the first housing number
Two apartments with different rents can cost the same once utilities, internet, insurance, laundry, furniture and commuting are included. Ask what is covered and read Ontario’s rental information before signing. A cheaper address that adds two long daily trips may not be cheaper for your household.
Use listings you can verify and inspect the property when possible. Urgency is not a reason to send a deposit. A short period in temporary accommodation may be expensive per night, yet still cost less than escaping an unsuitable lease.
Price the commute you will really make
Count trips to work, school, childcare, appointments and groceries. Compare transit fares and passes with the occasional taxi or ride service. For a car, add insurance, fuel, parking, maintenance, registration and financing; the monthly payment is only one line.
Try the route at the time you expect to travel and check evening or weekend service too. Winter walking and service gaps can change a route that looked easy on a map.
A couple may find a lower rent outside the city and then spend much of the difference on two daily GO Transit fares. Compare the monthly housing and commute totals together before signing a lease.
Build food, phone and health costs from quotes
Use a one-week grocery list based on foods your household actually buys, then add household supplies and occasional meals away. Compare plans for mobile service and internet, including activation, device and cancellation costs. Avoid financing more equipment than your budget can carry.
Confirm provincial health coverage and what it excludes. Budget for prescriptions, dental, vision and private insurance where appropriate. Family needs, existing conditions and waiting periods can materially change the amount.
Two real weeks will improve the estimate
Track what you spend for fourteen days without trying to defend or judge each item. Separate arrival purchases from recurring bills, then replace your estimates with the real rent, grocery and transportation figures. Keep receipts needed for returns, warranties or taxes.
Government guidance notes that housing and utilities often take a large share of income and that major cities can be expensive. Treat that as a prompt to research your own situation, not as a percentage that every household must match. A settlement organization may also help you identify local services for which you qualify.
Include children, education and seasonal costs
Families should identify school registration, childcare, transportation, clothing, recreation and meal costs separately. Availability can matter as much as price, particularly for childcare or specialized support. Contact the responsible school board or provider directly and ask which identity, address and immunization records are required.
Toronto weather changes the budget. Winter clothing, heating, snow-related transportation and indoor activities may create costs not visible in a summer estimate. Annual fees and holidays also make some months higher than others, so divide irregular expenses across the year rather than treating them as surprises.
Protect credit and avoid settlement scams
A newcomer promotion is not automatically the lowest-cost bank or phone product. Compare the price after any introductory period, cancellation terms and whether credit is being used. Pay agreed bills on time, review statements for errors and avoid borrowing solely to build a credit score.
Pause when a landlord, employer, bank caller or government impersonator demands immediate payment, gift cards, cryptocurrency or account credentials. Verify through a phone number or website you find independently. Keep an emergency amount accessible so one fraudulent or disputed payment does not endanger rent or food.
Decide what can wait
Arrival pressure can make every purchase feel urgent. Rank items as required now, useful this month or optional later. Furniture, vehicle ownership, long phone contracts and a larger apartment are easier to evaluate after employment and commute patterns are known. Borrowing for non-essential setup can turn a short-term choice into a long obligation.
Review subscriptions and recurring charges at the end of each month. Direct some savings to predictable annual expenses and some to a true emergency reserve. If income or housing changes, rebuild the budget from current facts rather than trying to preserve the original plan at any cost.
What to do now
- Prepare low, expected and high three-month budgets.
- Compare total housing-plus-commute costs.
- Review actual spending after two weeks.
Where this guide stops
Prices vary by household and neighbourhood, so this guide cannot replace quotes gathered for the move you are planning.
Official sources
Continue reading
More in this topic
 08Sep
How to work with an immigration consultant in Canada
How to verify a representative, agree on the work and keep control of your immigration file.
Read more 08Sep
How Canadian immigration works: a map of the system
Understand the difference between temporary status, permanent residence, selection systems and the evidence required for an application.
Read more 08Sep
Your first 30 days in Canada: a newcomer checklist
Put identity records and health coverage first, then arrange money, housing and settlement services during your first month in Canada.
Read more